
Micron (MU) Q4 2026 Earnings: Revenue Up 379%, Deposits $12.75B

By Chad Hartman
Published · Last updated
Micron (MU) reported Q4 FY2026 revenue of $54.23 billion, up 379.3% year over year, and diluted EPS of $32.87, up about 1,062%, for the 14-week quarter ended September 3, 2026 (8-K released September 30; 10-K filed October 9, 2026). The release says its strategic customer agreements provide "added confidence in the durability of Micron's financial performance." The 10-K sizes that durability: $12.75 billion of customer deposits repayable from 2029 to 2031, and roughly $33 billion of obligations falling in the next twelve months, less than this one quarter's revenue.
| Field | Value |
|---|---|
| Company | Micron ($MU) |
| Quarter | Q4 FY2026, period ended September 3, 2026 |
| Earnings release | September 30, 2026 (Form 8-K) |
| 10-K filed | October 9, 2026 |
| Revenue | $54.23 Billion (+379.3% YoY) |
| Diluted EPS | $32.87 (+1,061.5% YoY) |
| Operating margin | 80.7% (+48.4 pts YoY) |
| Operating cash flow (TTM) | $89.67 Billion |
| Full-year revenue | $133.19 Billion (+256.3% YoY) |
| Customer deposits received (FY2026) | $12.75 Billion |
Micron Q4 2026 Revenue, EPS and Margins
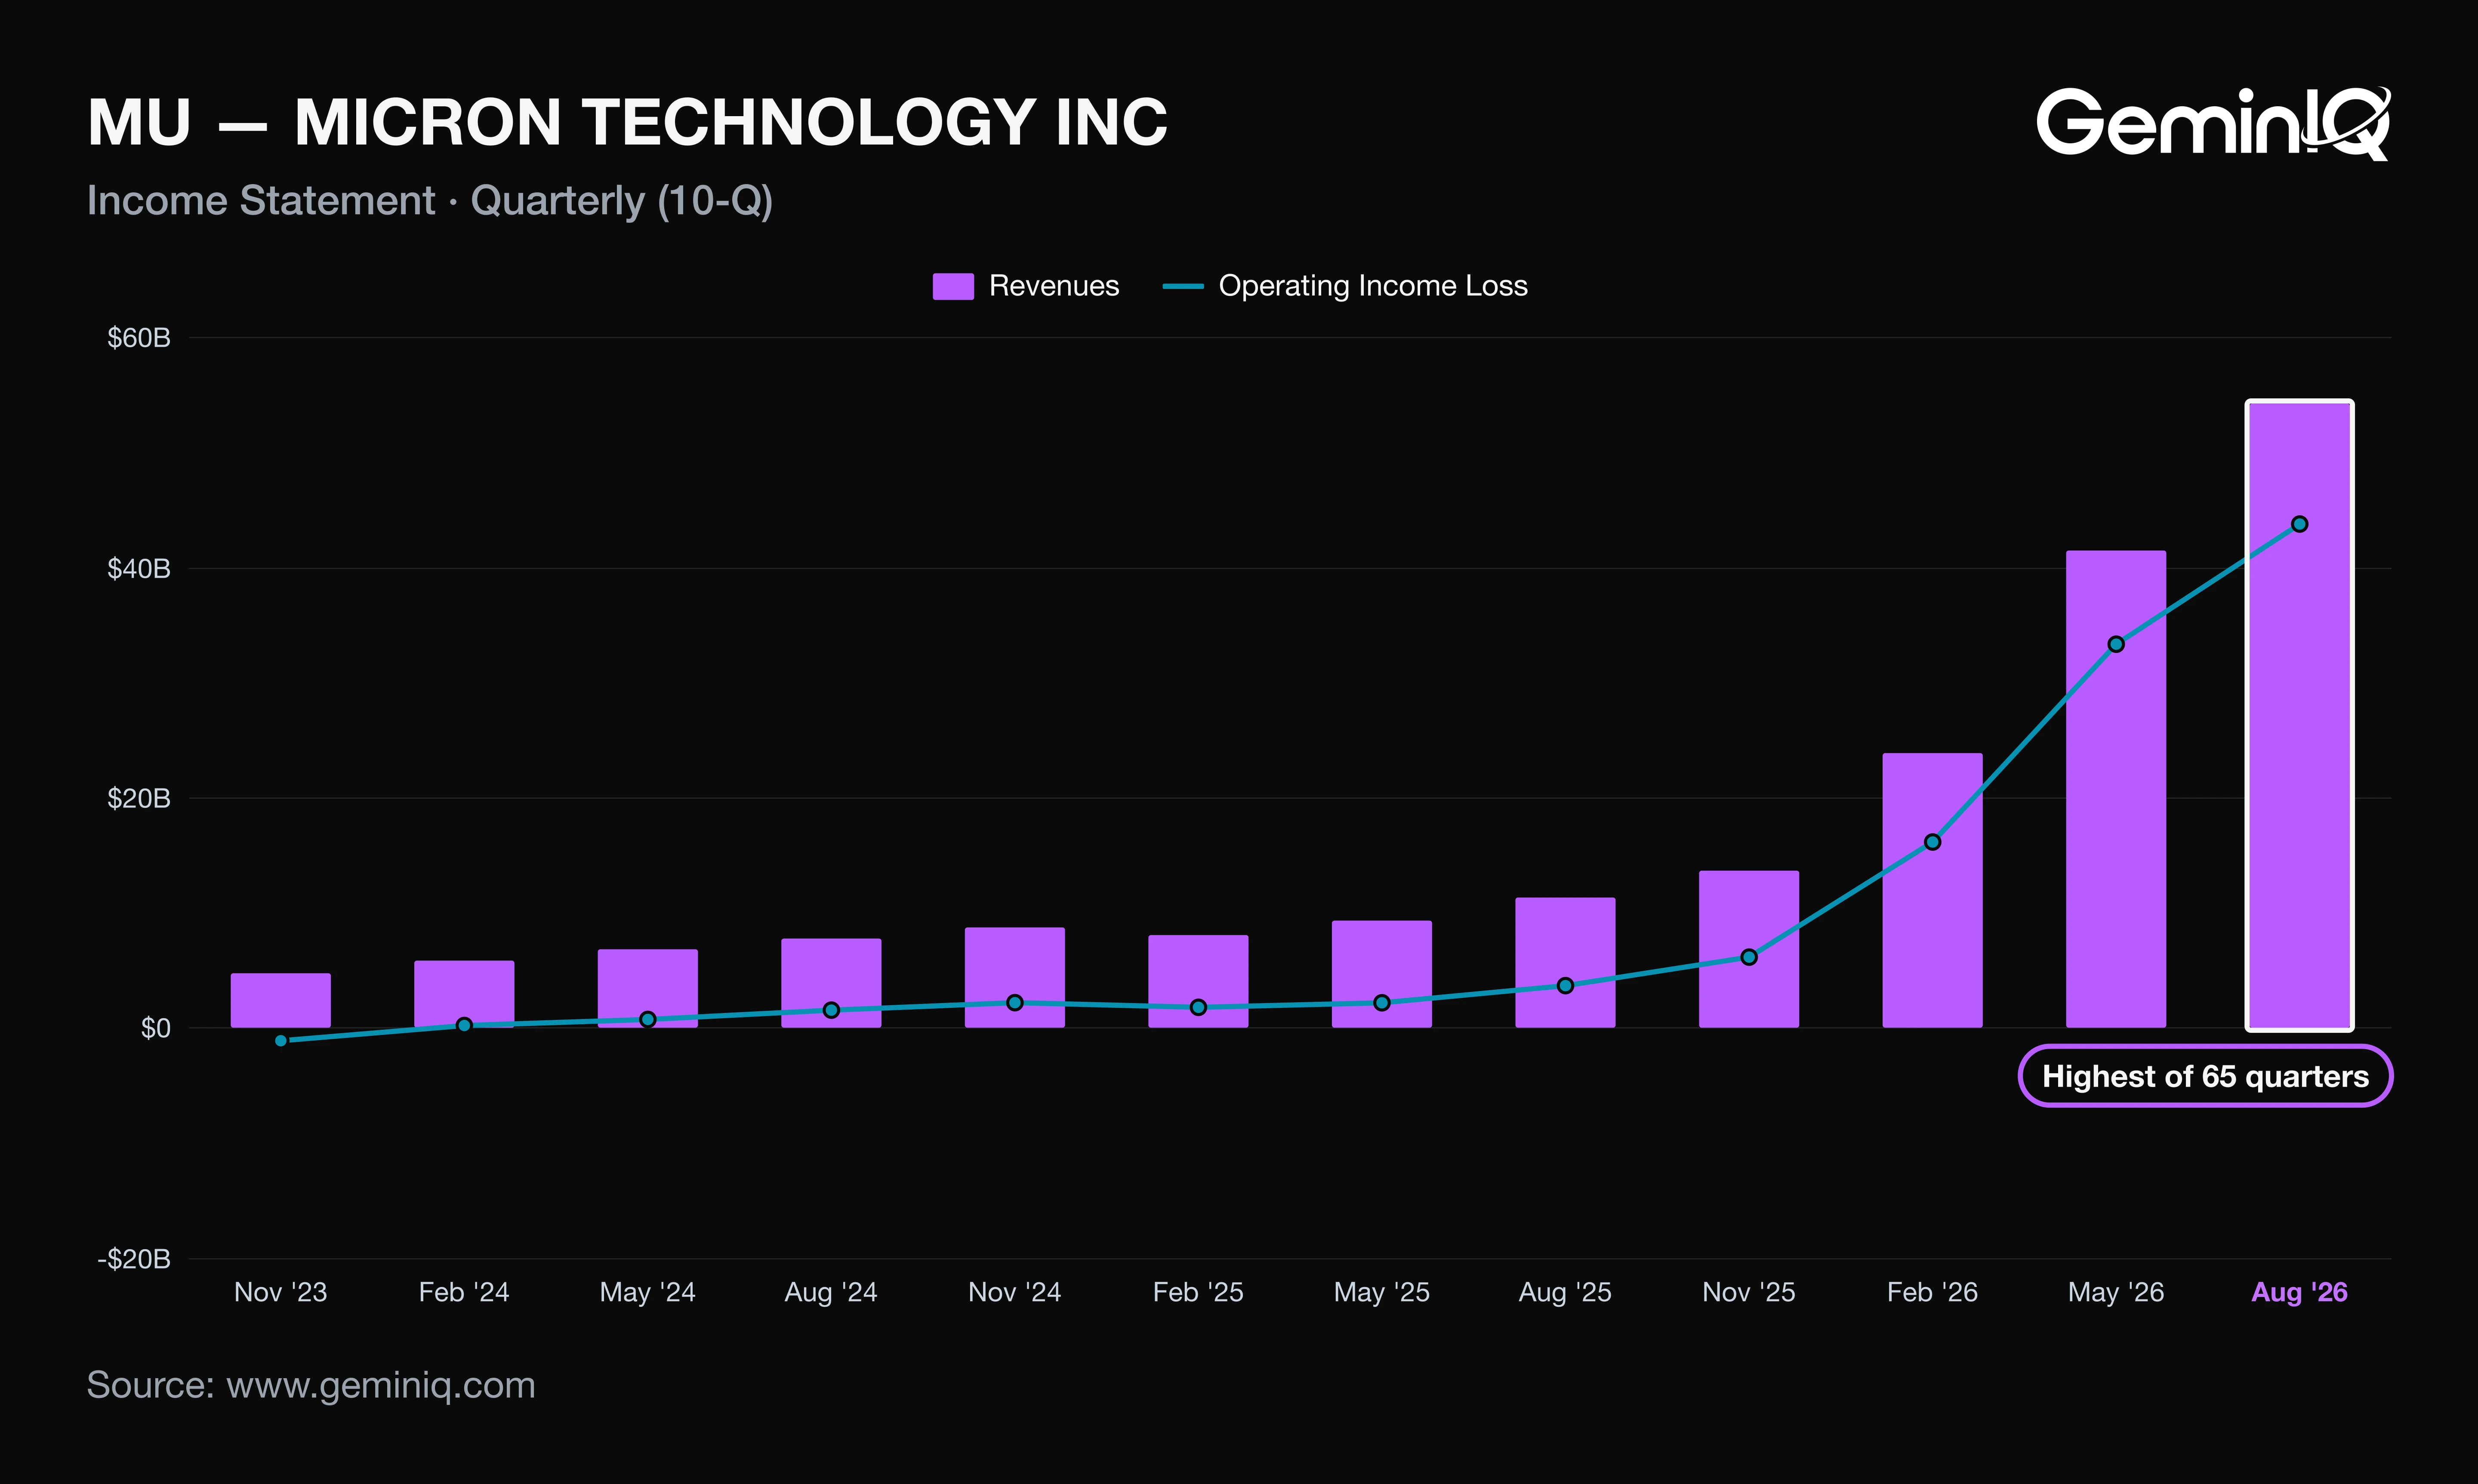
Micron's Q4 2026 revenue was $54.23 billion, up 379.3% from $11.32 billion a year earlier and 30.8% from the prior quarter, and diluted EPS was $32.87 against $2.83. Price built the quarter, and an extra week flatters the sequential comparison.
The Data: Gross margin reached 86.8% and operating margin 80.7%, each the highest of the last 16 quarters and of 65 since 2009. Operating income was $43.75 billion. For the full year, the 10-K reports DRAM sales up 252% on an approximate 180% rise in average selling prices and a mid-20% range rise in bit shipments.
Why: Revenue grew about 4.8-fold and operating margin about 2.5-fold, together a 12-fold gain against EPS's 11.6-fold; a higher share count and tax rate took a little back. Fiscal 2026 had 53 weeks, and the extra one sits here: the quarter ran from May 28 to September 3, 14 weeks against 13, so revenue per week rose about 21.5% sequentially, not 30.8%. Bit shipments grew about a quarter. The rest was price, and a margin built on price lasts as long as the price does.
What Micron's FY2026 10-K Shows Beyond the Press Release
Micron's 10-K puts the transaction price allocated to remaining performance obligations at approximately $134 billion, with about one-fourth expected as revenue over the next twelve months. That is roughly $33 billion for the coming year, against $54.23 billion reported in Q4 alone.
The Data: A year earlier these obligations were "not material." Now $134 billion sits in take-or-pay agreements, of which $13 billion is already booked as contract liabilities, mostly customer deposits. Micron received $12.75 billion of deposits in 2026, nearly all scheduled for repayment between 2029 and 2031, and $7 billion of customer letters of credit stand behind them.
Why: The filing excludes agreements without fixed pricing or price bands and says the obligations are "not expected to be indicative of future revenue," so spot-priced sales sit outside the $134 billion. Management says gross margins at floor pricing should run "meaningfully above our peak quarterly margins in any past cycle"; the filing gives no figure to test that claim. Today the release's durability claim describes the contracts, and the revenue is mostly outside them.
Micron Q4 2026 Operating Cash Flow, Debt and Customer Deposits
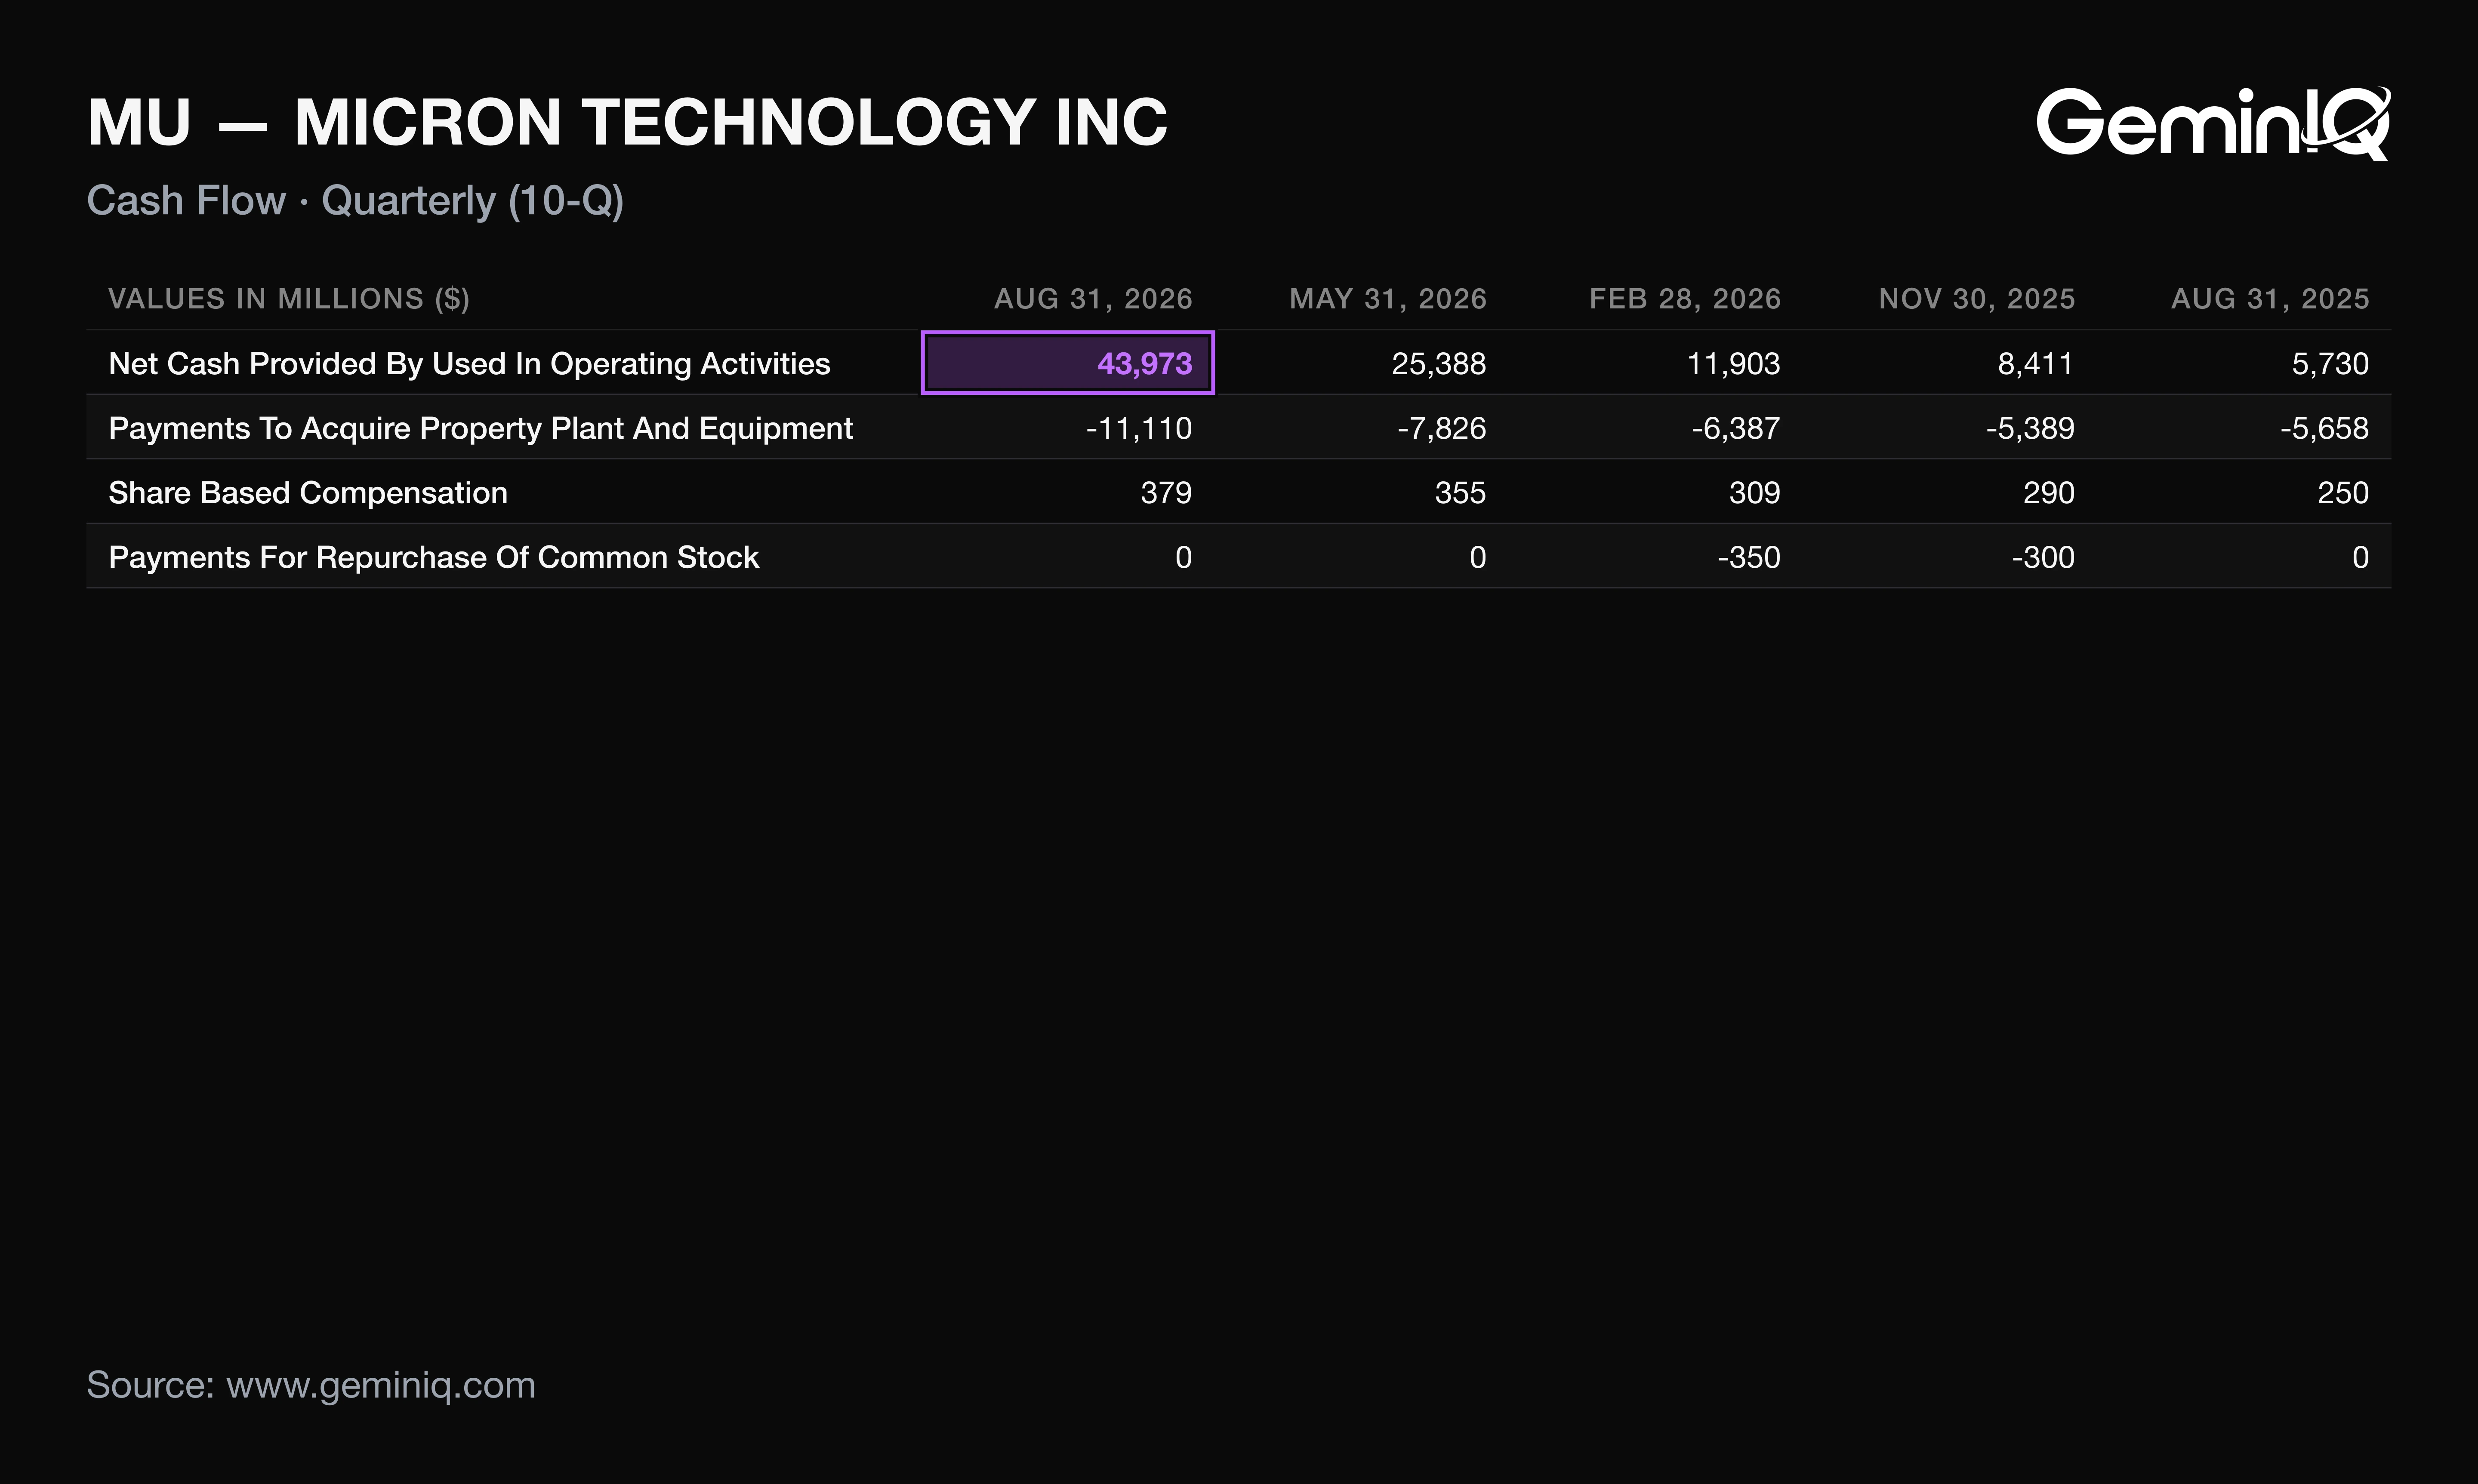
Micron's Q4 2026 operating cash flow was $43.97 billion, up 667% from $5.73 billion a year earlier, and free cash flow (operating cash flow less capital expenditure) was $32.86 billion, the highest of the last 16 quarters.
The Data: Operating cash flow exceeded the quarter's $37.70 billion of net income by $6.27 billion. Capital expenditure reached $11.11 billion, also a 16-quarter high. Over the year, Micron repaid $10.04 billion of debt, cutting principal from $14.6 billion to $5.2 billion, while receiving $12.75 billion of customer deposits; net financing cash flow was +$630 million. Noncurrent customer contract liabilities rose from $142 million to $12.9 billion on the 8-K balance sheet. GeminIQ's pre-calculated Net Debt to EBITDA is -0.31x on a trailing basis.
Why: Deposits are booked in financing, so they did not inflate operating cash flow. They did replace debt: repayment of one creditor funded by prepayment from customers, who get cash back in 2029 to 2031 only if they meet purchase minimums. Even adding the $12.9 billion to $5.2 billion of debt leaves far less than the $73.45 billion of cash and marketable investments, so liquidity is not the concern. A balance sheet that retires debt with customer prepayments has not become debt-free; it has changed creditors.
Micron's Fiscal Q1 2027 Guidance After Q4
In its 8-K, Micron guided Q1 FY2027 revenue to $61.5 billion ± $1.5 billion and GAAP diluted EPS to $37.84 ± $1.00. The prior quarter's guide shows how the company's ranges have fared.
The Data: For Q4 the company guided revenue of $50.0 billion ± $1.0 billion and GAAP EPS of $30.73 ± $1.00. Actual revenue of $54.23 billion cleared the top of that range by $3.23 billion, and EPS of $32.87 cleared its $31.73 top. Operating expenses did not follow: GAAP $3.30 billion against about $1.86 billion guided, and non-GAAP $2.57 billion against $1.65 billion, even excluding the $500 million patent license charge the 8-K removes.
Why: The revenue overshoot of about $4.2 billion above the midpoint paid for an expense overshoot of about $1.4 billion. The new guide implies 13.4% more revenue than Q4, but if Q1 runs 13 weeks, revenue per week is about 22% higher. GAAP gross margin is guided to about 85.95%, below Q4's 86.8%, and EPS rises 15% because GAAP operating expenses are guided back to about $2.31 billion. The guide leans on price and volume, not margin.
How MU Stock Has Moved After Past Earnings Reports
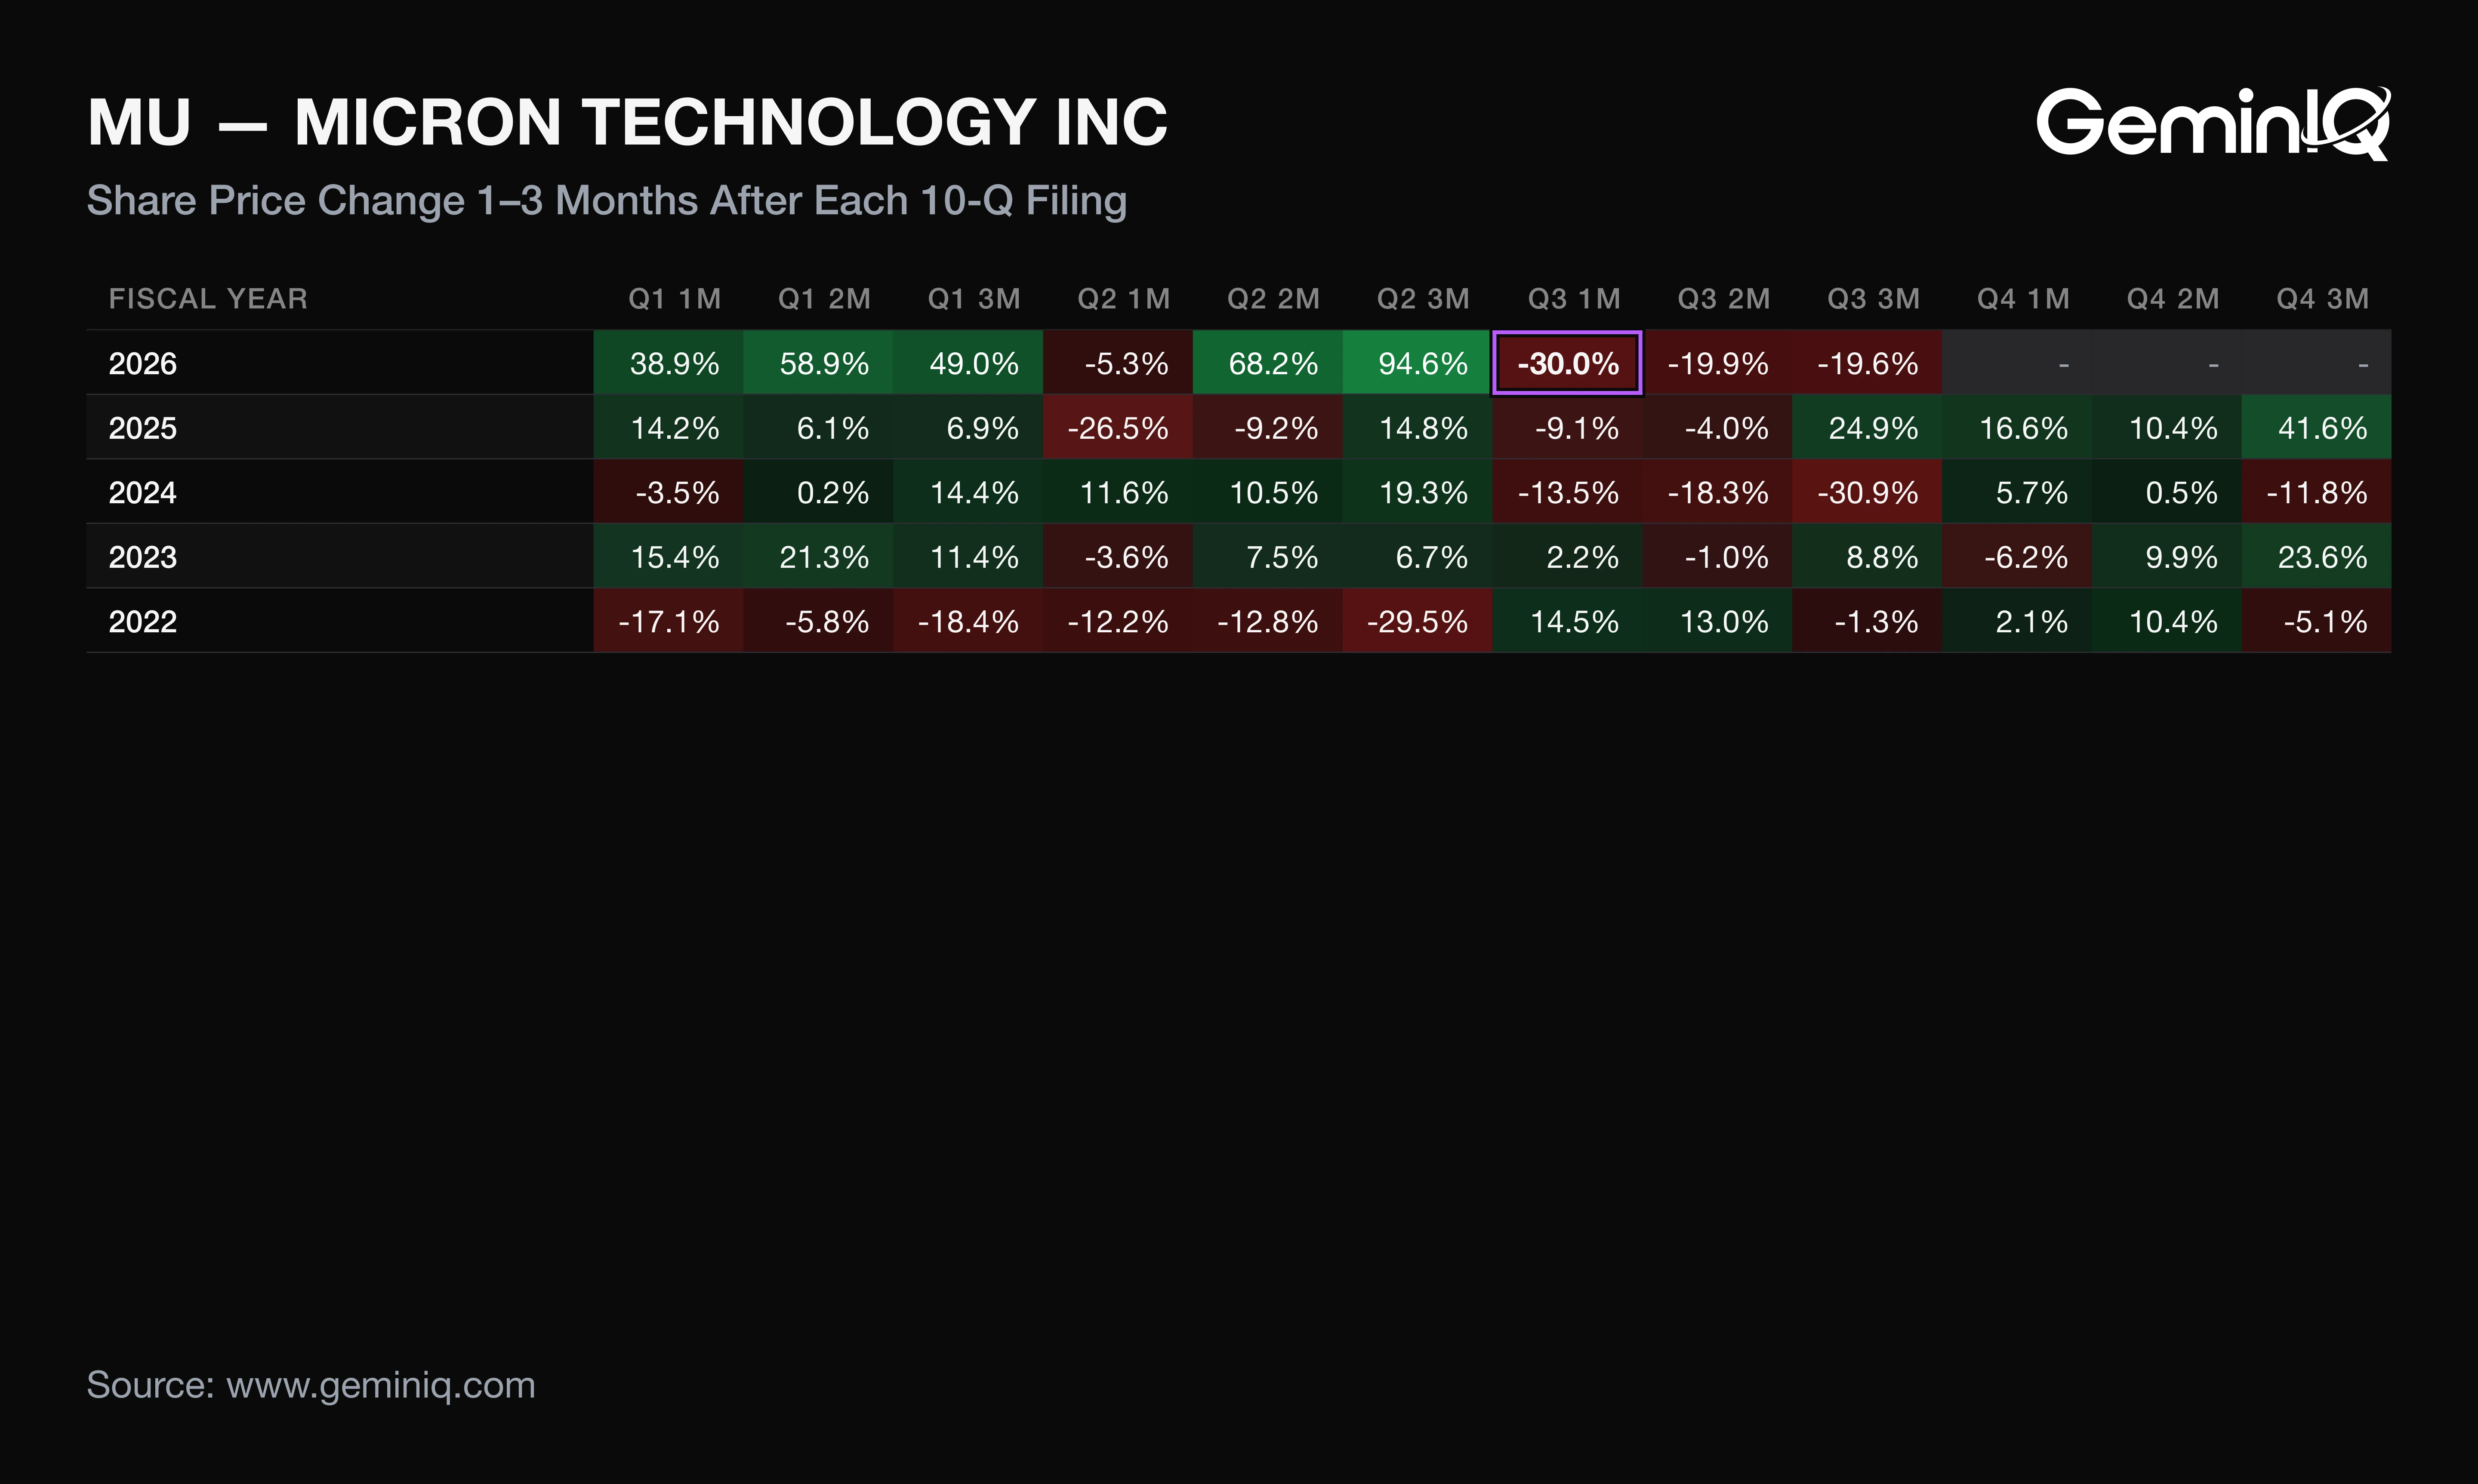
Across the last 12 Micron 10-Q filings with a completed one-month window (filed October 2023 to June 2026), the median one-month return was -4.4%, positive after 5 of 12, while the median three-month return was +17.0%, positive after 9 of 12.
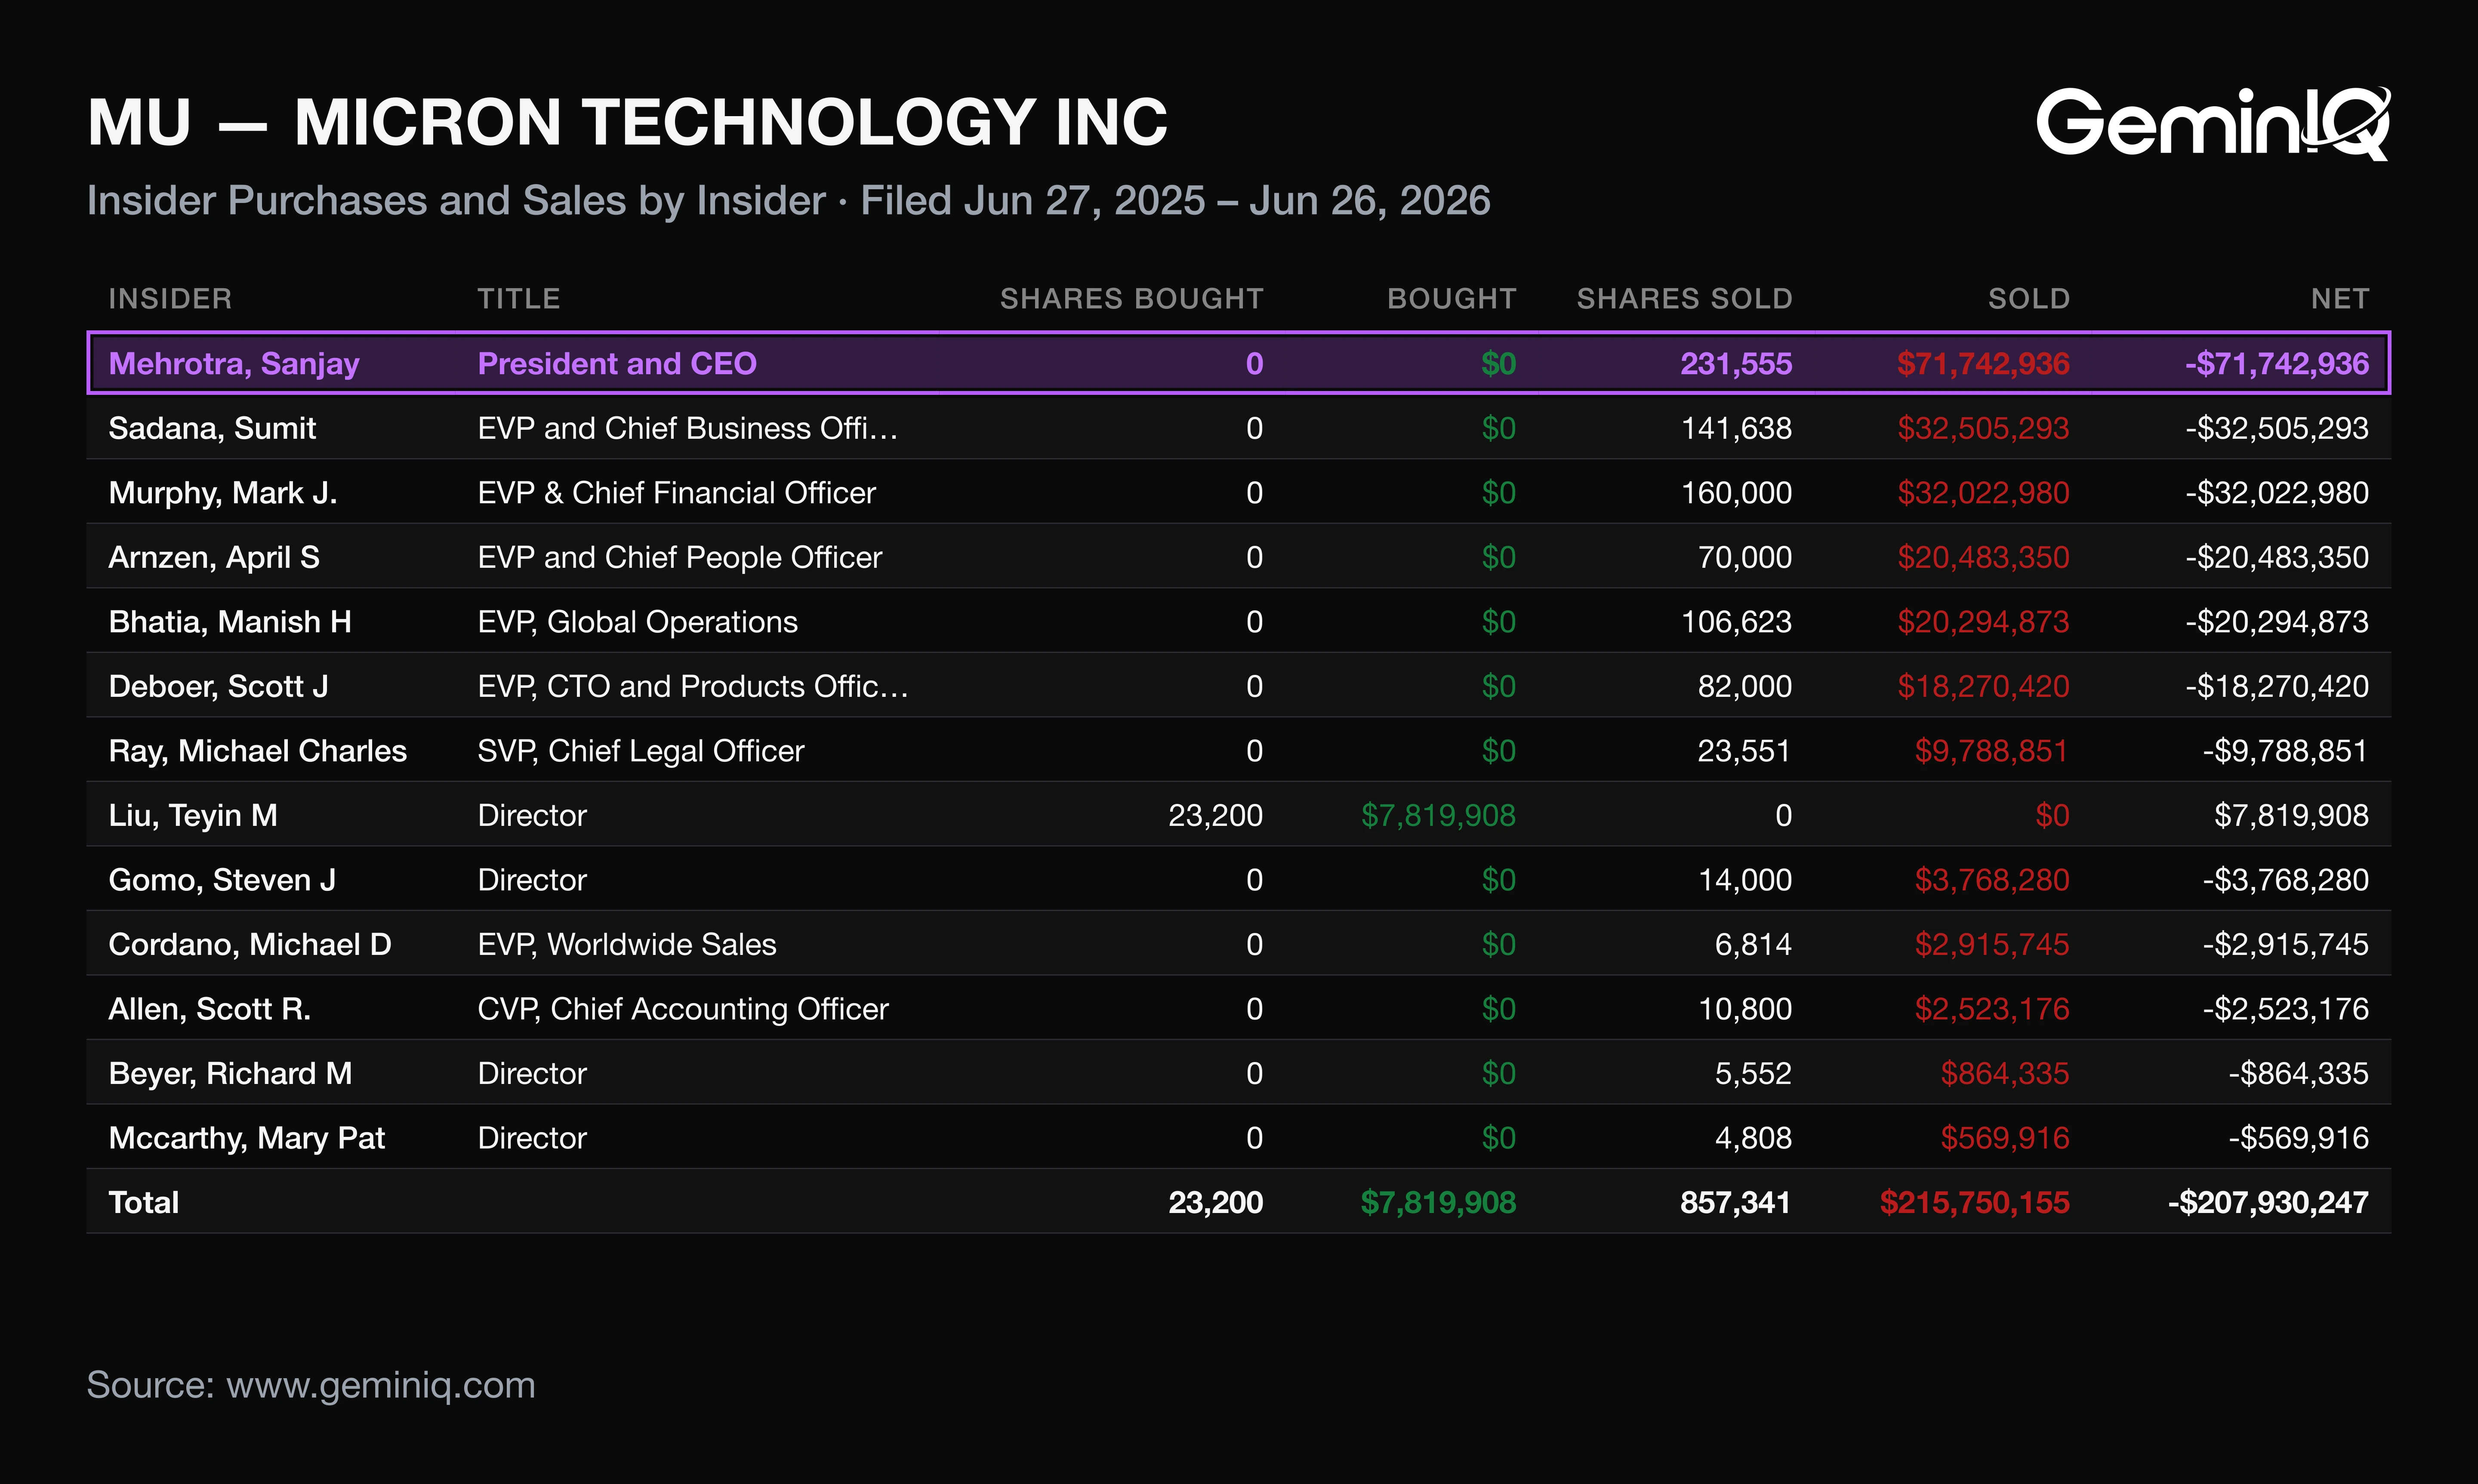
The Data: The one-month range ran from -30.0% (FY2026 Q3, filed June 25, 2026) to +38.9% (FY2026 Q1). The three-month range ran from -30.9% to +94.6%. After the past three fourth-quarter filings, one-month returns were -6.2%, +5.7% and +16.6%. This filing's windows have not elapsed. In the 12 months of Form 4 data ending June 26, 2026, insiders filed 45 sales worth $215.8 million and two purchases worth $7.8 million, against 20 sales worth $17.8 million in the prior 12 months; CEO Sanjay Mehrotra accounted for $71.7 million, or 33%.
Why: The gap between a median one-month dip and a median three-month gain is the pattern in the GeminIQ Earnings Reaction Heat Map; it is a historical association, not a forecast, and it describes how Micron's stock moved after its past filings. Insider sales ran 22 to 1 over purchases by count. The Insider Transactions data ends June 26, 2026, so it does not cover the weeks after the release. When a record quarter arrives, the number worth pricing is the share of it the customer has already signed for.
Frequently Asked Questions
When does Micron report earnings?
Micron released its Q4 FY2026 results on September 30, 2026 and filed its 10-K on October 9, 2026. Last year the company filed its first-quarter FY2026 results on December 18, 2025, a pattern from the filing record and not a forecast of the next date.
Does Micron pay a dividend?
Yes. Micron declared a quarterly dividend of $0.15 per share on September 30, 2026, payable October 29, 2026 to holders of record on October 14. It paid $173 million in Q4 and $610 million in fiscal 2026, up from $522 million, after raising the rate from $0.115 to $0.15 in the third quarter.
Is Micron doing well financially?
Micron's trailing net profit margin was 63.80% against 22.84% a year earlier, per GeminIQ's pre-calculated Net Profit Margin. GeminIQ's Return on Invested Capital (ROIC) was 100.94% against 15.44%, and its Current Ratio was 3.31x. Cash and marketable investments totaled $73.45 billion at fiscal year-end.
What was Micron's fiscal 2026 revenue?
Micron's fiscal 2026 revenue was $133.19 billion, up 256% from $37.38 billion, with net income of $84.97 billion and diluted EPS of $74.33. DRAM contributed $100.68 billion and NAND $31.79 billion.
Wall Street's data. Main Street's price.
Institutional terminals charge thousands a year for as-filed accuracy. GeminIQ gives you the same thing for a fraction of the cost: financials built directly from raw SEC EDGAR filings, not third-party APIs, with full XBRL traceability back to the original 10-K or 10-Q. No normalized guesswork, just calculated metrics, charts, screeners, and watchlists built on numbers exactly as the company reported them. Start researching now at GeminIQ.com.
All financial figures cited in this article reference Micron Technology, Inc.'s fiscal 2026 10-K (filed October 9, 2026, period ending August 31, 2026), with guidance and management commentary drawn from the company's Form 8-K earnings release (filed September 30, 2026). All SEC filings are publicly available at SEC EDGAR and SEC EDGAR.
Disclaimer: The content in this blog is for educational and entertainment purposes only and does not constitute financial, legal, or tax advice. Investing involves risk, including the loss of principal. The views expressed are my own and not intended as financial advice or a guarantee of future performance.